Executive Summary
The disruption in the Strait of Hormuz in early 2026 exposed the vulnerability of Pakistan’s fuel supply chain. Pakistan heavily relies on imported crude oil, petroleum products, and LNG, with majority of this supply volume concentrated around Gulf producers, and relying on maritime routes that are vulnerable to geopolitical disruption. Between July and March FY2026, Pakistan imported approximately 13.9 million metric tons of crude oil and petroleum products at a cost of approximately $8.9 billion; imports account for approximately 25% of crude-oil requirements, 30% of diesel, and nearly 70% of petrol, while Qatar and the UAE supply all of Pakistan’s LNG imports. In the course of these crises, the crude-oil inventory of Pakistan roughly fell to only 11 days, requiring emergency supply arrangements via Saudi Arabia’s Yanbu port, increased stock management, and special import financing needs.
This Policy Viewpoint, therefore, recommends that instead of crisis-driven solutions, Pakistan should adopt a permanent fuel-supply resilience centered on four mutually reinforcing approaches. First, develop a phased Strategic Petroleum Reserve, beginning with a credible emergency buffer and progressively adding required commercial and refinery reserves. Second, establish diversification across suppliers, contracts, cargo terminals, shipping routes, and payment methods before a disruption occurs. Third, improve refinery crude-slate flexibility and petroleum logistics to ensure that alternative sources can be processed, stored, and supplied essentially. Fourth, design and implement a centralized fuel-supply emergency framework which includes real-time monitoring, predetermined escalation mechanisms, contingency fund, and inter-departmental coordination. These measures, together, will provide Pakistan with time, alternatives, local flexibility, and institutional readiness. The objective is to efficiently manage external energy reliance more resiliently, so that any disruption, in a particular supply route, does not translate into domestic fuel shortages and macroeconomic instability.
1. The Policy Problem
Pakistan’s fuel security dilemma is not grounded alone in the imports. It is instead combination of foreign dependency, limited supply routes, insufficient stock capacities, and absence of institutional contingency plans.
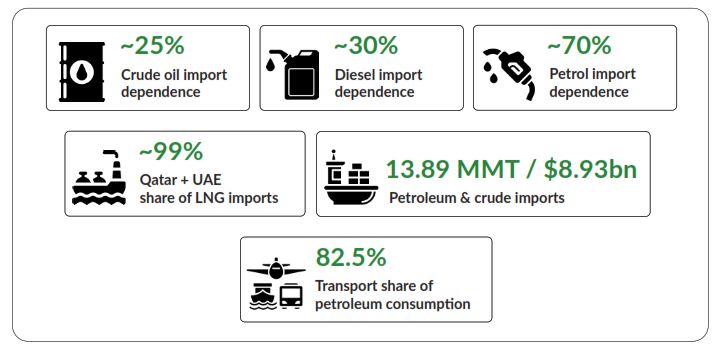
In addition, the exposure risk also varies significantly amongst petroleum products. In March 2026, the Petroleum Division informed the Senate Standing Committee that Pakistan imports around 25% of its crude oil requirements, 30% of its diesel, and roughly 70% of its gasoline. All these supplies primarily passing through the Persian Gulf and the Strait of Hormuz. The committee was also briefed that Pakistan held approximately 392,000 tonnes of crude oil, 404,000 tonnes of diesel and 564,000 tonnes of petrol at the time.
Economic vulnerability is also evident in the country. Pakistan consumed roughly 13.64 million metric tons of petroleum products from July to March FY2026. The major chunk of around 82% has been consumed by the transport sector accounting for around 11.25 million tons, while the petroleum imports totaled around 13.89 million tons and cost nearly $8.93 billion during same period2. As a result, fuel supply interruptions have a rapid impact on freight charges, agricultural logistics, passenger mobility, and pricing across the economy.
Following petroleum products, LNG acts is another layer of fuel concentration. According to Kpler, Qatar and the UAE jointly account for nearly 99% of Pakistan’s LNG supplies3. This becomes more concerning since around 93% of Qatar’s and 96% of the UAE’s LNG exports generally pass Hormuz, and there is no comparable physical bypass route capable of redirecting such a volume of LNG to global markets.
Figure 1. Pakistan’s Exposure to Imported Fuels and Concentrated Supply
Source: Senate of Pakistan, Secretary Petroleum Division briefing to the Senate Standing Committee on Petroleum, 2026; Pakistan Economic Survey 2025-26; Kpler (2026)
Pakistan’s economy heavily depends on continuous fuel supply, while its fuel-security framework has been designed predominantly for regular commercial conditions. As such, the Hormuz crisis revealed a structural challenge. The insufficient commercial stockpiles, long-term import contracts, and established Gulf supply links and international shipping operations caused sever energy crises. They offer significantly low protection when a geopolitical shock impacts physical availability, freight, insurance, financing, and procurement lead times all at once.
Therefore, underlying policy objective should be beyond securing energy resources and should be focused on resilient interdependence, with sufficient buffers, alternative supply options, domestic flexibility, and institutional capacity to absorb external shocks before it leads to domestic scarcity and macroeconomic instability.
2. External Shock Transmission
An external fuel shock hits Pakistan through a several interrelated channels. A geopolitical crisis may initially disrupt traditional suppliers, shipping routes, or significant maritime chokepoints. Even where physical cargoes are still accessible, increased security threats may increase international oil and LNG prices, tanker freight charges, and war-risk insurance premiums. For an importing economy, these increases immediately increase foreign exchange demand and the value of individual import transactions. Banking limits, letters of credit, and supplier-credit arrangements may thus form part of the energy security dilemma. During the 2026 crisis, Pakistan had to change its banking procedures in order to allow imports of crude oil, petroleum products, and LNG.
Figure 2. External Shock Transmission Mechanism
| 01 | International geopolitical crisis |
| 02 | Disruption of suppliers and maritime routes |
| 03 | Higher crude oil, LNG, freight and insurance costs |
| 04 | Pressure on foreign exchange and import financing |
| 05 | Lower inventories and procurement uncertainty |
| 06 | Higher domestic fuel prices |
| 07 | Higher transport, agriculture, industry and logistics costs |
| 08 | Inflation and macroeconomic stress |
Source: Author’s illustration based on Pakistan Economic Survey 2025-26 and State Bank of Pakistan (2026)
If replacement cargoes are delayed, local inventories begin to decrease, while procurement uncertainty increases. Subsequent pressure then passes to the downstream, causing higher gasoline, diesel, and other fuel prices. Since petroleum is used in transportation, agriculture, industry, and logistics, price hikes also impact the food prices as a result of production costs, and overall inflation. The supply-chain mechanism of fuel supplies implies that resilience cannot be based on a single action. Strategic fuel supplies alone cannot withstand prolonged disruption; even the alternate supplies become insufficient if cargoes cannot be financed or processed; and infrastructure offers little protection in the absence of institutions capable of coordinating an emergency response.
3. Fuel-Supply Resilience Gaps
Gap 1: Limited Strategic Buffer
Pakistan maintain commercial petroleum inventory equivalent to 20 days by Oil Marketing Companies (OMCs), as per requirement OGRA, to meet domestic sales. These reserves ensure market continuity, but they are not equivalent to the sovereign Strategic Petroleum Reserve designated for exceptional conditions. However, the Hormuz disruption of March 2026 caused the crude oil reserves to fall for only 11 days despite a greater diesel buffer4. This has exposed the institutional weakness where Pakistan lacks an adequately developed supplementary layer of sovereign emergency reserves that can be released in as per national security requirements.
Gap 2: Concentrated Suppliers and Maritime Supply Routes
Pakistan has longstanding relations with Gulf state which facilitate advantageous access to energy resources of region. However, the resources are geographically concentrated and given Hormuz situation has become volatile. The Hormuz route accounted roughly one-quarter of global seaborne oil transit and in 2025 alone about 20 million barrels of crude oil passed per day The available capacity to bypass the strait via Saudi and UAE crude pipeline is estimated to be between 3.5 and 5.5 million barrels per day5. The existing crisis, however, exposed this route as most vulnerable leading to considering Yanbu and Fujairah as alternative routes to add redundancy but evidently cannot replace regular Hormuz shipments which is centered around major energy resources. NG is significantly less flexible because Qatar has no equivalent bypass route.
Gap 3: Limited Refining and Fuel-Logistics Flexibility
Domestic refining may reduce reliance on imported finished petroleum products, however refining itself is still dependent on crude supply. Resilience thus depends not only on increasing capacity, but also on ensuring that refineries can process a wide range of technically compatible crude oils and that ports, storage facilities, pipelines, and inland distribution networks can adapt to shifting supply patterns.
Gap 4: Reactive Crisis Preparedness
Pakistan showed significant crisis management capacity in 2026. High-level committees monitored stocks, cargoes, prices, and distribution; OGRA improved supply monitoring; Saudi Arabia was approached for Yanbu supplies; and the SBP changed import-financing procedures. The challenge is that several of these systems were more active after the disturbance occurred. The immediate policy goal is to transform emergency readiness into permanent contingency planning.
Table 1. Resilience Gap and Policy Response
| Resilience gap | What the 2026 crisis exposed | Policy response |
| Limited strategic buffer | Crude stocks fell to around 11days | R1. Strategic Petroleum
Reserve |
| Supplier and route concentration | Heavy Gulf/Hormuz exposure; Yanbu
activated during crisis |
R2. Supply & route
diversification |
| Refining and logistics rigidity | Alternative supplies still require compatible refineries, ports and pipelines | R3. Refining & logistics flexibility |
| Reactive crisis management | Monitoring, financing and coordination intensified after disruption began | R4. Institutionalized Crisis preparedness |
Source: Author’s synthesis based on the analysis presented in this Policy Viewpoint
These four gaps provide the basis for the policy recommendations developed in the following section.
4. Policy Recommendations
R1. Build a Phased National Petroleum Stockholding System
Pakistan should develop a multi-layered national petroleum stockholding architecture instead of treating commercial inventories and strategic reserves alike. The first layer should be mandatory commercial stocks maintained by OMCs and refineries for normal market continuity; the second operational layer should be refinery feedstock inventories; and the third which is currently underdeveloped layer should be a state-controlled ring-fenced Strategic Petroleum Reserve for exceptional external disruptions.